Running a Print Business
How Much Should You Charge for Printed T-Shirts?
Sep
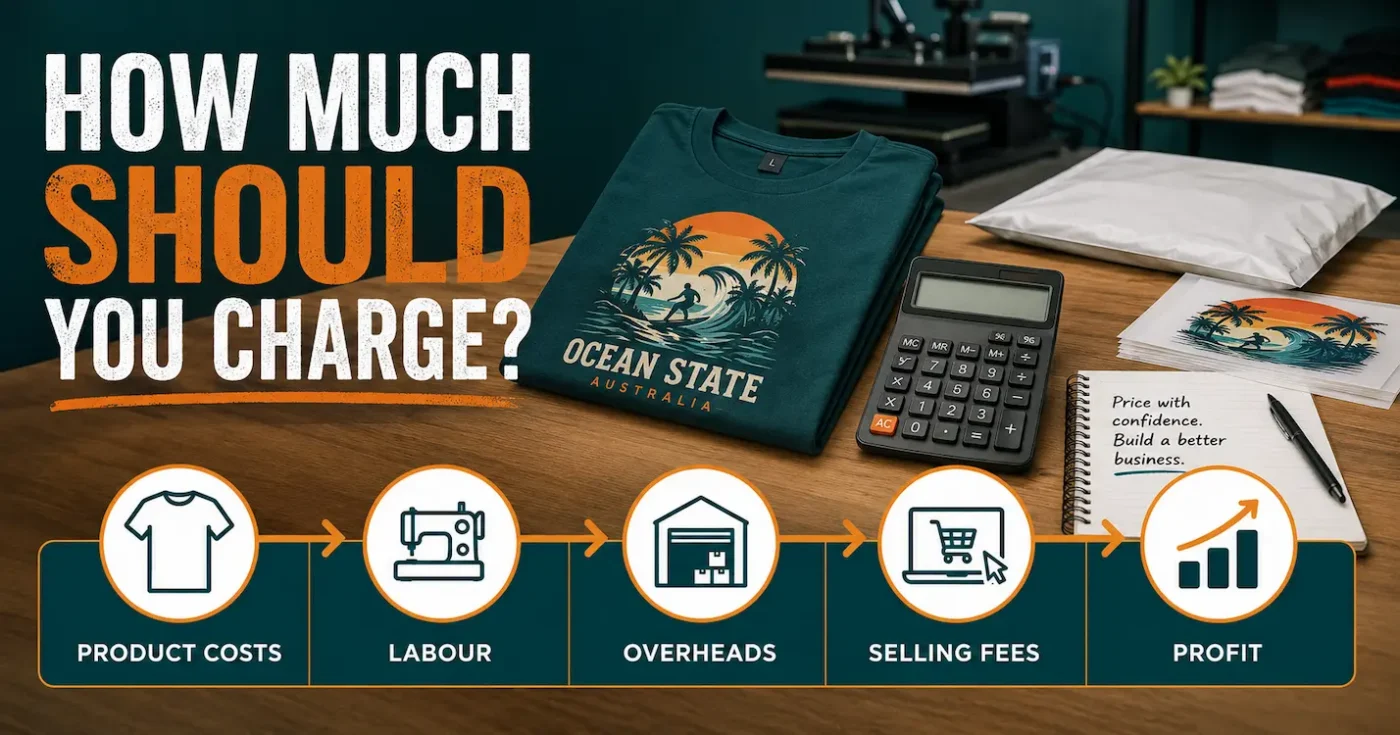
There is no single correct selling price for every printed T-shirt. Your price needs to cover the blank garment, transfer, labour, packaging, wastage, selling costs and a fair share of business overheads—then leave enough profit to make the business worthwhile. Competitor prices can provide context, but your own costs must come first.
Quick pricing formula:
Selling price = total unit cost ÷ (1 − target margin − percentage selling fees)
Use decimal values in the formula: 40% becomes 0.40 and 3% becomes 0.03. If you are registered for GST, calculate consistently using GST-exclusive costs and revenue, then add GST to the consumer selling price.
This article provides general business information for Australian T-shirt sellers. It is not individual accounting, tax or legal advice. Check current government guidance and speak with a qualified adviser about your circumstances.
Contents
Why there is no magic T-shirt price
A basic promotional shirt, a carefully branded fashion tee and a personalised one-off product can all use a blank T-shirt and DTF transfer, yet customers may value them very differently. The appropriate price depends on:
- garment brand, fit, fabric and weight;
- print size, number of print positions and transfer finish;
- order quantity and production efficiency;
- artwork, personalisation and customer-service time;
- packaging and presentation;
- where the product is sold;
- your brand position and audience; and
- the level of profit required to keep the business sustainable.
The older rule of simply doubling the blank-and-print cost can miss labour, rent, website subscriptions, failed garments and marketplace commissions. It may produce an acceptable price by accident, but it does not show whether the product is actually profitable.
If you are still developing the wider business model, begin with our guide to starting a T-shirt business with DTF transfers.
Calculate the true cost of one printed T-shirt
Start by listing every cost required to create, sell and supply one finished garment. Keep fixed-dollar costs separate from percentage fees because they behave differently in the final formula.
| Cost category | Examples | How to calculate it |
|---|---|---|
| Blank garment | T-shirt purchase price, inbound freight and supplier charges | Landed cost per garment, not just the catalogue price |
| Printing | DTF transfer, cover sheet wear, heat-proof tape and other consumables | Actual transfer and consumable cost per finished shirt |
| Labour | Ordering stock, artwork handling, pressing, quality checking, packing and administration | Minutes per item ÷ 60 × fully loaded hourly rate |
| Packaging | Mailer, bag, label, tissue, swing tag or care card | Cost of the packaging actually used for that order |
| Wastage and reprints | Pressing mistakes, damaged blanks, test garments, returns and replacements | Historical loss cost spread across successful items |
| Design and setup | Illustration, photography, samples, listing creation and launch assets | Recover upfront cost over a conservative expected sales quantity |
| Overheads | Rent, power, insurance, software, accounting, equipment and marketing | Allocate a fair amount per unit or productive hour |
| Selling fees | Marketplace commission, payment processing, listing and transaction fees | Fixed fee plus percentage of the selling price |
| Delivery subsidy | Any freight or fulfilment cost not separately charged to the customer | Actual delivery cost less the amount recovered at checkout |
Use recent invoices and real sales data wherever possible. Small costs matter when they repeat on every order. A $1.50 packaging cost across 1,000 shirts is $1,500—not an insignificant extra.
Your time is a cost, even when you work alone
New business owners often treat their own time as free. That can make an unprofitable product appear successful. If the business grows and you later employ someone to complete the same work, the price may no longer cover production.
Time a normal order from start to finish. Include:
- checking and preparing the order;
- receiving and sorting garments;
- cutting and positioning transfers;
- pre-pressing, pressing, peeling and final pressing;
- quality control and folding;
- packing, labelling and dispatch;
- customer messages and changes; and
- cleaning and maintaining the work area.
Use a realistic hourly labour rate. If you employ staff, the cost is more than the wage paid into their bank account; your accountant can help calculate the complete employment cost relevant to your business.
Allocate overheads and hidden business costs
Overheads keep the business operating but cannot always be attached directly to one shirt. Examples include rent, electricity, insurance, website hosting, design subscriptions, bookkeeping, advertising and equipment depreciation.
One practical approach is:
Overhead per unit = expected overheads for the period ÷ realistic number of saleable units
Use a realistic quantity, not the maximum number you hope to sell. If actual sales are lower than the forecast, each item must carry a larger share of the overhead.
Alternatively, production businesses can allocate overhead by productive labour hour. Whichever method you use, apply it consistently and compare the estimate with actual profit-and-loss results.
Allow for failure and rework
A business will occasionally damage a blank, misplace a transfer or need to replace an item. Track these events. If 3 out of every 100 shirts require a complete reprint, the cost of those failures must be recovered across the successful items rather than disappearing from the calculation.
Good artwork and fitting procedures reduce avoidable loss. Our essential T-shirt design tips and DTF pressing tips can help prevent common problems.
Profit margin and mark-up are not the same
This distinction causes many pricing mistakes.
- Mark-up measures profit as a percentage of cost.
- Gross margin measures gross profit as a percentage of selling price.
Suppose a shirt costs $20 and sells for $30. The $10 gross profit represents:
- a 50% mark-up on the $20 cost; but
- a 33.3% gross margin on the $30 selling price.
Adding 40% to cost does not create a 40% margin. To calculate a selling price from a target gross margin:
Selling price = unit cost ÷ (1 − target margin)
If percentage selling fees also apply:
Selling price = fixed unit cost ÷ (1 − target margin − percentage selling fees)
This produces a starting price. You must still check GST treatment, fixed transaction fees, market position and whether the resulting price supports the business.
Worked T-shirt pricing example
The following figures are illustrative only. They are not recommended prices and do not represent the cost of every DTF T-shirt.
| Example fixed cost | Per shirt |
|---|---|
| Blank garment and inbound freight | $8.00 |
| DTF transfer and consumables | $4.00 |
| Production and administration labour | $4.50 |
| Packaging | $1.50 |
| Wastage and replacement allowance | $1.00 |
| Design and product-development recovery | $1.00 |
| Allocated overhead | $3.00 |
| Total fixed unit cost | $23.00 |
For a target gross margin of 40%, before percentage selling fees:
$23.00 ÷ (1 − 0.40) = $38.33
If the sales channel instead charges a total variable selling fee of 3%:
$23.00 ÷ (1 − 0.40 − 0.03) = $40.35
The calculation is being performed before GST. If the seller is registered for GST and the $23 cost base has been calculated consistently excluding claimable GST, 10% GST would then be added to determine the consumer price:
$40.35 × 1.10 = $44.39 including GST
The business might choose a market-appropriate displayed price such as $44.50 or $44.95, but should then recalculate the real margin rather than assuming the rounded figure still produces exactly 40%.
Important: Do not mix GST-inclusive supplier costs with GST-exclusive sales revenue. The correct treatment depends on whether you are registered and entitled to claim input tax credits. Ask your accountant to check your spreadsheet.
GST and displaying T-shirt prices in Australia
As at September 2026, an Australian business generally must register for GST when its GST turnover reaches $75,000 or more. GST turnover is not the same as profit. Businesses below the threshold may be able to register voluntarily. Check the current Australian Taxation Office GST registration guidance for your situation.
If you sell to consumers, advertised prices generally need to show the minimum total price as a single clear figure, including GST and unavoidable or pre-selected fees. The Australian Competition and Consumer Commission price-display guidance explains the current requirements.
Payment fees still need to be included in your internal costing even when you choose not to add a separate card surcharge. If you do surcharge customers, check the current ACCC and payment-network rules before publishing the charge.
Research the market without blindly copying competitors
Competitor research answers an important question: does your calculated price make sense within the market you are targeting? It does not replace your cost calculation.
Compare products on a like-for-like basis:
- garment brand, fabric weight, fit and construction;
- print method, size, number of positions and finish;
- artwork or personalisation included;
- production time and delivery charge;
- packaging, labelling and presentation;
- refund, replacement and customer-service offer; and
- whether the advertised price includes GST and unavoidable charges.
A $25 shirt and a $45 shirt may not be equivalent. One might use a lightweight generic blank with a small print and basic packaging, while the other uses a heavier recognised garment, a large front-and-back print and careful presentation.
Decide whether your brand is competing through low price, fast production, original artwork, premium garments, local service, personalisation or a specialised audience. Your price should support that position. Our article on social media and emerging T-shirt trends can help you think about audiences and demand without chasing every short-lived trend.
Price for the sales channel
The same shirt can have different economics depending on where it is sold.
Your own website
Allow for hosting, apps, payment processing, photography, advertising, packing and customer support. Owning the website may reduce marketplace commission, but it does not make customer acquisition free.
Online marketplaces
Include listing fees, transaction commissions, payment fees, promoted-listing costs and any marketplace-funded discounts charged back to the seller. Read the complete fee schedule rather than relying on the headline percentage.
Markets and events
Allocate stall fees, travel, staff time, display equipment, payment processing and unsold stock. Divide event costs by a realistic sales estimate, then compare it with actual results after the event.
Wholesale
A wholesale price must leave room for the retailer while still covering your cost and profit. This usually requires minimum quantities, efficient production, simplified packaging or other operating differences. Do not offer a wholesale discount calculated from retail price without checking whether the remaining amount covers the wholesale order’s real costs.
Build discounts and promotions into the model
If you regularly offer 10%, 15% or 20% promotions, calculate the profit at the discounted price before launching the sale.
Discounted price = normal price × (1 − discount percentage)
A $40 shirt discounted by 20% sells for $32. If its total cost is $23, the dollar return falls from $17 to $9 before considering any fee differences. Sales volume must increase substantially for that promotion to create the same total return.
Bundles can still work when they reduce real costs. Packing three shirts into one parcel, processing one transaction and using a larger efficient transfer layout may lower the cost per unit. Calculate those actual savings before selecting the bundle discount.
When ordering transfers, a carefully filled DTF gang sheet can reduce the transfer cost per design. That efficiency can improve margin, support a genuine quantity discount or allow investment in a better garment.
Make sale claims genuine
Do not advertise a “was” price that was never a genuine selling price, temporarily raise a price to create an artificial discount, or run a supposedly limited offer indefinitely. Australian Consumer Law requires pricing and promotional claims to be accurate and not misleading.
Review your T-shirt prices regularly
Supplier costs, freight, wages, rent, payment fees and advertising performance change. Review prices whenever a major input changes and on a regular schedule, such as quarterly.
Track these figures by product and sales channel:
- units sold;
- average selling price after discounts;
- blank and printing cost;
- labour time;
- wastage and replacement rate;
- selling and payment fees;
- shipping cost and amount recovered;
- gross profit per item; and
- profit remaining after overheads.
If a popular product is not producing enough return, you can raise the price, reduce unnecessary costs, improve production efficiency, change the garment, redesign the print or discontinue it. More sales do not automatically mean more profit.
Compare our ready-to-press DTF transfer options when calculating the printing component of your next product.
Frequently asked questions about pricing printed T-shirts
How much should I charge for a printed T-shirt?
Calculate the complete cost of producing and selling the shirt, then use a target-margin formula and compare the result with equivalent products in your market. A universal dollar figure cannot account for different garments, prints, labour, channels and brand positions.
What costs should be included in a T-shirt price?
Include the landed blank garment, transfer or printing, consumables, labour, packaging, design recovery, wastage, overhead allocation, selling fees and any delivery cost you do not recover separately.
What is the formula for calculating a T-shirt selling price?
A useful starting formula is: total unit cost divided by one minus your target margin and percentage selling fees. Keep GST treatment consistent and include fixed transaction fees separately.
What is the difference between margin and mark-up?
Mark-up compares profit with cost, while margin compares profit with selling price. A $20 item sold for $30 has a 50% mark-up but a 33.3% gross margin.
Should I copy competitors’ T-shirt prices?
No. Use competitor prices as market context, but compare equivalent quality and service. Their costs, sales volumes and strategy may be very different from yours.
Should my website price include GST?
If you are registered for GST and selling to consumers, the displayed total price generally needs to include GST and unavoidable or pre-selected fees. Check current ATO and ACCC guidance for your circumstances.
How do I price custom or personalised T-shirts?
Add the artwork, administration and production time created by personalisation. A setup charge, personalisation fee or higher unit price may be appropriate when the additional work does not reduce with quantity.
How often should I review my prices?
Review them regularly—quarterly is a useful starting rhythm—and immediately when important costs or fees change. Compare estimated unit economics with actual business results.
Is a 50% mark-up enough?
Not necessarily. A 50% mark-up produces a 33.3% gross margin, and that may still need to fund overheads, tax and future investment. Test the resulting price against your complete costs and required business return.
